Medicare Open Enrollment is open: Oct. 15 – Dec. 7. Get a free, no-obligation plan review from a licensed local specialist.
Book your free consultation nowOrca Insurance Group · Winter Park, FL · Serving all of Central Florida
Medicare Insurance
Medicare Supplement, Medicare Advantage & Part D (Prescription)
For individuals 65 years old and over.
No cost, no obligation · Phone, video, or in our Winter Park office
Book your free Medicare consultation now
Pick a day and time that suits you. A licensed Medicare specialist will review your options by phone, video, or at our Winter Park office. All times are Eastern Time (Orlando).
Open Enrollment ends December 7. Changes take effect January 1, 2027.
Prefer to talk now? Call (407) 672-2467
Medicare Open Enrollment Period (AEP)
Oct. 15 – Dec. 7
Last day to make changes: December 7.
New coverage starts January 1, 2027.
What is Medicare Open Enrollment Period (AEP)?
Plans can change their costs, covered drugs and provider networks every year, so it’s worth reviewing your coverage for 2027. During Medicare Open Enrollment you can switch from Original Medicare to a Medicare Advantage Plan or back, switch from one Medicare Advantage Plan to another, and join, switch or drop a Medicare drug plan (Part D). During the rest of the year you generally need to qualify for a Special Enrollment Period (SEP) to make these changes.
Good to know: if you leave a Medicare Advantage Plan for Original Medicare, you may not have a guaranteed right to buy a Medicare Supplement (Medigap) policy. We’ll walk you through that before you switch.
Medicare, explained
The basics of who qualifies, what each part covers, and how Medicare Supplement and Medicare Advantage plans differ.
Eligibility
Who is eligible for Medicare?
Generally, Medicare is available for people age 65 or older, younger people with certain disabilities & people with End Stage Renal Disease (ESRD) (permanent kidney failure requiring dialysis or transplant).
Part A
What does Medicare Part A cover?
Medicare Part A (hospital insurance) covers inpatient hospital care, skilled nursing facility, lab tests, surgery, home health care, hospice.
Part B
What does Medicare Part B cover?
Medicare Part B (Medical Insurance) coverage includes doctor and other health care providers’ services and outpatient care.
Part D
What does Medicare Part D cover?
Medicare Part D covers prescription drugs. Before purchasing it’s a good idea to review the drug formulary (list of covered medications) to make sure your medications are covered.
Note: Don’t go 63 days in a row without a Part D plan or other credible coverage. You will have to pay a late enrollment fee.
Medigap
What is a Medicare Supplement?
Medicare Supplement Insurance, also known as a Medigap policy, helps fill “gaps” in Original Medicare and is sold by private companies.
Part C
What is a Medicare Advantage Plan?
Medicare Advantage Plans, sometimes called “Part C” or “MA Plans,” are an “all in one” alternative to Original Medicare. They are offered by private insurance companies approved by Medicare. If you join a Medicare Advantage Plan, you still have Medicare. These Medicare Advantage “bundled” plans include Medicare Part A (Hospital Insurance) & Medicare Part B (Medical Insurance), & usually Medicare prescription drug (Part D).
2026 Medicare costs at a glance
What Medicare costs in 2026
Part A · Hospital
$0
Monthly premium for most people who (or whose spouse) paid Medicare taxes for at least 10 years.
Part B · Medical
$202.90
Standard monthly premium, with a $283 annual deductible.
Part D · Prescriptions
$2,100
Yearly cap on what you pay out of pocket for covered drugs. Plan premiums don’t count toward the cap.
Higher-income beneficiaries pay more for Part B and Part D (called IRMAA). Medicare announces 2027 amounts each fall, and we’ll walk you through the current figures in your review.
Good to know before you compare
A few options many people don’t realize they may have.
Extra Help
Help paying for prescriptions
If your income and resources are limited, Extra Help can lower your Part D premium, deductible and copays. In 2026, copays are no more than $5.10 for generics and $12.65 for brand-name drugs. People with Medicaid or a Medicare Savings Program usually get it automatically. You can apply at SSA.gov, or we can help.
Part B premium
Plans that lower your Part B premium
Some Medicare Advantage plans reduce the monthly Part B premium you pay, often called a “Part B giveback.” Availability depends on your ZIP code and the plan, and these plans can differ in other ways, so it’s worth comparing the full picture.
SNPs
Special Needs Plans
Special Needs Plans are Medicare Advantage plans built for specific groups: people with certain chronic conditions (C-SNPs), people who have both Medicare and Medicaid (D-SNPs), and people who live in a nursing home or similar facility (I-SNPs).
Your free review, step by step
What happens in a free review?
1
Share your details
Your ZIP code, your doctors, your prescriptions and the coverage you have now.
2
Compare your options
We check whether your doctors and hospitals, such as AdventHealth or Orlando Health, are in network, look up your drugs on each plan’s list, and compare total costs side by side.
3
Decide what’s right for you
There’s no cost and no obligation. If your current plan still fits, that’s a fine answer too.
What to have ready
✓ Your ZIP code
✓ Your Medicare card, or your Part A and Part B start dates
✓ Names of your doctors, specialists and hospitals
✓ Your prescriptions, with doses, and your preferred pharmacy
✓ Your current plan card and its Annual Notice of Change, if you have one
Local, licensed, and in person
Real people, right here in Winter Park
When you call Orca, you talk to a licensed agent from our Winter Park office, not a national call center. Stop by, call, or book a time online.
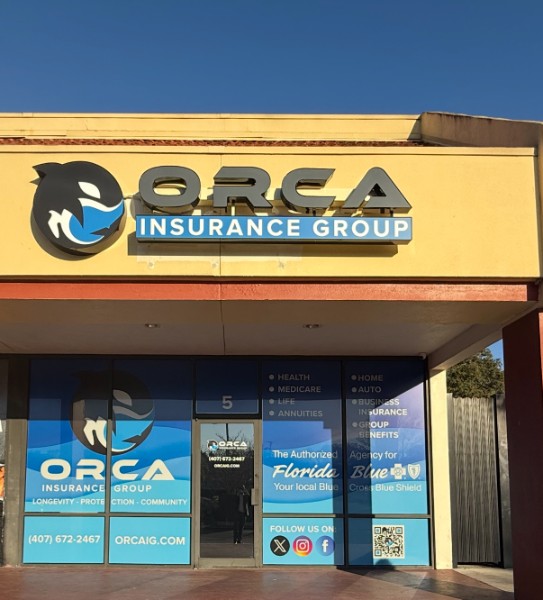
Our Winter Park office
2335 Temple Trail, Ste 5
Winter Park, FL 32789
(407) 672-2467
Tim Sabat
Principal Agent, Orca Insurance Group
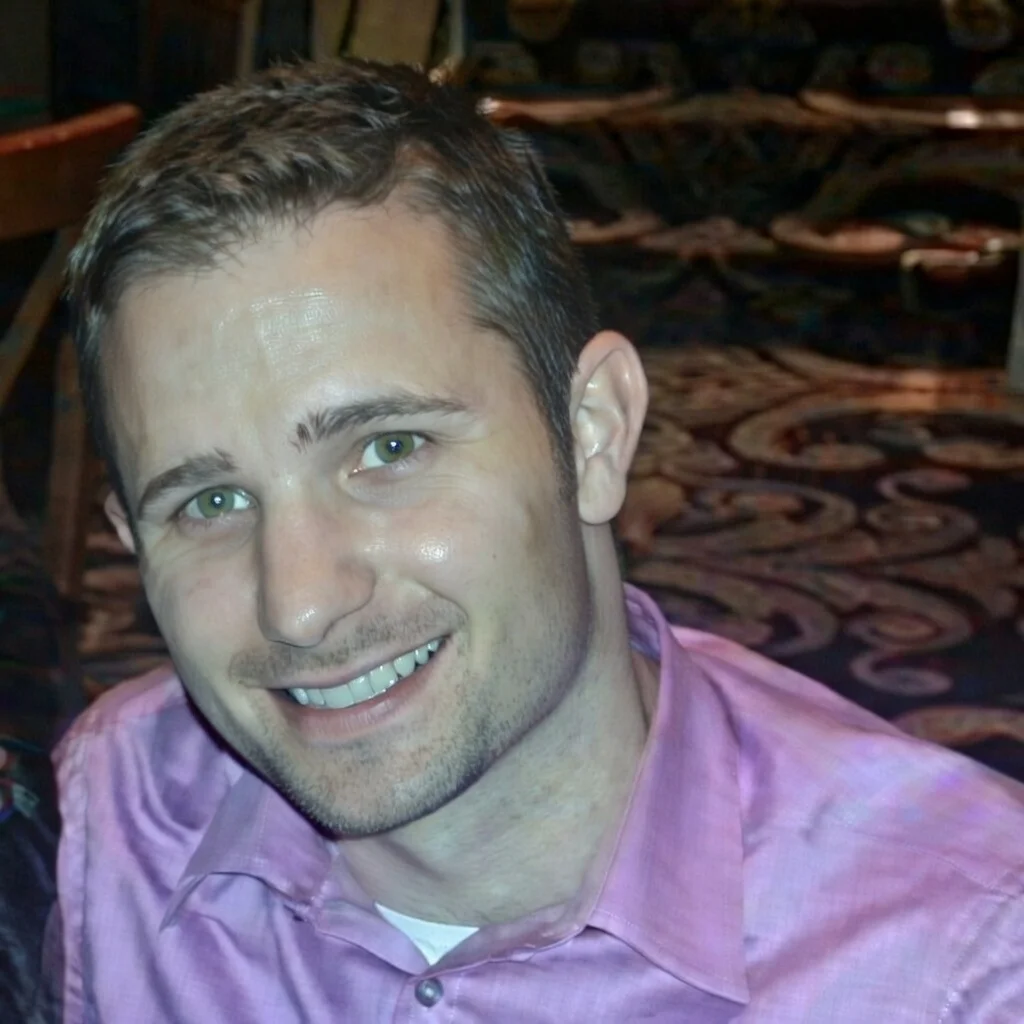
Caleb Sabat
Insurance Agent & Broker, Orca Insurance Group
Talk to a Local Medicare Broker
Free Medicare consultation — we compare Medicare Supplement, Medicare Advantage, and Part D plans from top carriers so you can enroll with confidence. No cost, no obligation. Serving Winter Park, Orlando, and all of Central Florida.
Medicare Insurance in Winter Park & Orlando, FL
Turning 65 is a milestone — but navigating Medicare for the first time can feel overwhelming. With Original Medicare, Medicare Advantage, Medigap supplements, Part D prescription plans, and dozens of carriers competing for your business, how do you know what's right for you?
That's where having a local, independent Medicare broker makes all the difference. At Orca Insurance Group, we help Winter Park and Orlando seniors compare Medicare options side by side — at no cost to you. Our services are free because we're compensated by the insurance carriers, not by you.
Why Work with a Medicare Broker?
- We're free to use — Medicare brokers are paid by the carriers. You pay the same premium whether you enroll directly or through us.
- We're independent — Unlike captive agents who sell only one company's plans, we compare plans from multiple carriers to find the best fit.
- We know Central Florida — Provider networks, plan availability, and drug formularies vary by zip code. We know which plans work best in the Orlando and Winter Park area.
- We help year-round — Not just during enrollment. If you have a claims issue, need to switch plans, or have questions about coverage, we're here.
- We simplify the process — Instead of calling 10 insurance companies, you call us once. We do the comparison shopping for you.
Understanding the Parts of Medicare
Part A — Hospital Insurance
Covers inpatient hospital stays, skilled nursing facility care, hospice care, and some home health services. Most people get Part A premium-free if they (or their spouse) paid Medicare taxes for 10+ years.
Part B — Medical Insurance
Covers doctor visits, outpatient care, preventive services, medical equipment, and some home health services. The standard 2026 Part B premium is $185/month (income-adjusted). There's an annual deductible before coverage kicks in.
Part C — Medicare Advantage
An alternative to Original Medicare offered by private insurers. Bundles Part A + B (and usually Part D) into one plan, often with additional benefits like dental, vision, hearing, and fitness. Many plans have $0 premiums beyond your Part B payment.
Part D — Prescription Drug Coverage
Covers prescription medications. Available as standalone plans (with Original Medicare) or bundled into Medicare Advantage. Each plan has its own formulary — the list of drugs it covers — so matching your medications to the right plan is critical.
Medicare Supplement (Medigap) vs. Medicare Advantage
This is the biggest decision most new Medicare enrollees face. Here's how they compare:
| Feature | Medigap Supplement | Medicare Advantage |
|---|---|---|
| Monthly premium | Higher ($100-$300+/mo) | Often $0 beyond Part B |
| Out-of-pocket costs | Lower — covers most gaps | Copays and coinsurance apply |
| Doctor network | Any doctor who accepts Medicare | Usually network-restricted (HMO/PPO) |
| Prescription drugs | Separate Part D plan needed | Usually included |
| Extra benefits | No | Dental, vision, hearing, fitness |
| Best for | Frequent travelers, those who want doctor flexibility | Budget-conscious, those okay with a network |
Neither option is universally "better" — the right choice depends on your health needs, budget, medications, and preferred doctors. That's exactly what we help you figure out.
Medicare Enrollment Timeline
Initial Enrollment Period (IEP) — 7-month window around your 65th birthday (3 months before, your birth month, 3 months after). This is your first and best opportunity to enroll without penalties.
Annual Election Period (AEP) — October 15 through December 7 each year. You can switch Medicare Advantage plans, go back to Original Medicare, or change your Part D plan. Changes take effect January 1.
Open Enrollment Period (OEP) — January 1 through March 31. If you're already in a Medicare Advantage plan, you can switch to a different MA plan or go back to Original Medicare with a standalone Part D plan.
Special Enrollment Periods (SEP) — Triggered by life events like moving, losing employer coverage, or qualifying for Extra Help. These allow changes outside normal enrollment windows.
Medicare in the Orlando & Winter Park Area
Central Florida has a robust Medicare market with dozens of Medicare Advantage and Medigap plans available in Orange, Seminole, and Osceola counties. Major carriers serving the Orlando area include Humana, Aetna, UnitedHealthcare, Cigna, Devoted Health, and Florida Blue.
Plan availability, provider networks, and pricing vary by zip code — even within the Orlando metro area. A plan that works well in Winter Park may have a different network or premium in Kissimmee or Sanford. We match your zip code, doctors, and medications to find plans that actually work where you live.
More Common Medicare Questions
How much does Medicare cost in 2026?
Part A is typically premium-free. Part B is $185/month (standard; higher for high earners). Medicare Advantage plans often have $0 premiums beyond Part B. Medigap supplements range from $100-$300+/month depending on the plan letter and your age. Part D averages $35-$55/month.
Can I keep my doctor with Medicare?
With Original Medicare + Medigap, you can see any doctor nationwide who accepts Medicare. With Medicare Advantage, you'll need to use the plan's network (HMO or PPO). We verify your doctors are in-network before recommending a plan.
What if I'm still working at 65?
If you have employer coverage (from an employer with 20+ employees), you can delay Medicare Part B without penalty. You'll get a Special Enrollment Period when you leave your job or lose employer coverage. We help coordinate the transition so there are no gaps.
Do I need both Medicare and health insurance?
Once you're on Medicare, it becomes your primary coverage. If you have a Medigap supplement, it works alongside Medicare. If you choose Medicare Advantage, it replaces Original Medicare for your benefits. You don't need a separate health insurance plan on top of Medicare.
What's the Medicare "donut hole"?
The Part D coverage gap (donut hole) is the phase where you temporarily pay more for prescriptions after you and your plan have spent a certain amount. In 2026, with the Inflation Reduction Act changes, out-of-pocket prescription costs are capped at $2,000/year — a major improvement for seniors on expensive medications.
Free Medicare Consultation
Not sure which Medicare path is right for you? We'll compare your options and help you enroll — at no cost.
Our services are free. We're paid by the carriers, not by you.
Schedule a Free Review